The Real Counterparts: Method and Evidence
Hansa Mutual is fictional. Its headquarters in Hamburg, its 9,500 employees, its seven jurisdictions, its claims centre in Poland, its Mode 5 agents and every identifier in the ledger were invented for the series and are established only by the fourteen volumes. This chapter and the next do something different from the rest of the book: they ask whether the invention is plausible. Chapter 25 sets out the method and the evidence, which real organisations were chosen as comparators and why, which public sources were read, what they say, and what could not be found. Chapter 26 gives the verdict dimension by dimension.
Three rules govern the check. The real organisations are named here and in Chapter 26 only, and only as comparators. None of Hansa Mutual's facts is taken from any of them, and nothing in the dossier should be read as a description of them. A volume of the series is the source for a fact about Hansa Mutual and never for a fact about the real world, so the comparison runs one way: the fiction is held up against public sources, and the sources are not edited to fit the fiction. The check measures plausibility, not accuracy. A figure that is "generous" in Chapter 26 is not wrong, because an invented organisation cannot be wrong about itself; it is more mature, larger or more coherent than the evidence found for real organisations of the same kind.
All sources were retrieved on 16 November 2026, which is also the date of the dossier's other chapters. The profile facts quoted from the series come from AI Governance (Book 2), AI Operations (Book 10), AI Boss (Book 7) and AI Developer (Book 12) (2, Nordqvist, 2026) (10, Nordqvist, 2026) (7, Nordqvist, 2026) (12, Nordqvist, 2026).
What is being checked
The series describes Hansa Mutual as a mutual insurance group headquartered in Hamburg, with about 9,500 employees in Germany, the Netherlands, Sweden, Poland, Norway, the United Kingdom and Switzerland. It writes property and casualty, motor and, in some markets, life and supplementary health business. A shared AI platform in Hamburg and Frankfurt serves all seven markets, and a claims and operations centre in Poland handles claims for Germany, the Netherlands, Sweden and Norway, while the UK and Swiss entities handle claims locally and use the group platform in Germany (AI Governance, Chapter 1 and the profile) (2, Nordqvist, 2026). AI Boss gives the workforce by function and country: claims about 3,600 (about 1,400 at the Polish centre), sales and distribution about 2,100, underwriting about 1,100, IT about 1,300 and corporate functions about 1,400; Germany about 4,600, Poland about 1,700, the Netherlands about 900, the UK about 800, Sweden about 600, Switzerland about 500 and Norway about 400 (AI Boss, the people-management profile) (7, Nordqvist, 2026).
The check takes sixteen dimensions, grouped in four families.
| Family | Dimensions |
|---|---|
| Scale and form | headcount, legal form and seat, number of markets, product mix, premium volume |
| Supervision and law | the supervisory map of seven regimes, DORA incident experience, employee representation |
| AI in the business | generative AI assistants, group AI governance maturity, a claims-triage agent, an IT-operations agent with write access |
| Cost and organisation | cost per answer and envelope, daily claims volume, platform team size, the Polish claims centre |
For each dimension the method is the same. First, state what the series says and in which volume. Second, look for a published figure or statement from a real organisation of the same kind or from a supervisor. Third, record what the source says, in the source's own terms, and how the page was retrieved. Fourth, give a verdict in Chapter 26: credible when the series' claim falls within the range of the real references, generous when it is more mature, more integrated or larger than anything the references show, and thin when the check found too little to confirm or refute it. A fifth category, "no reference found", is reported in this chapter and folded into thin in the verdict.
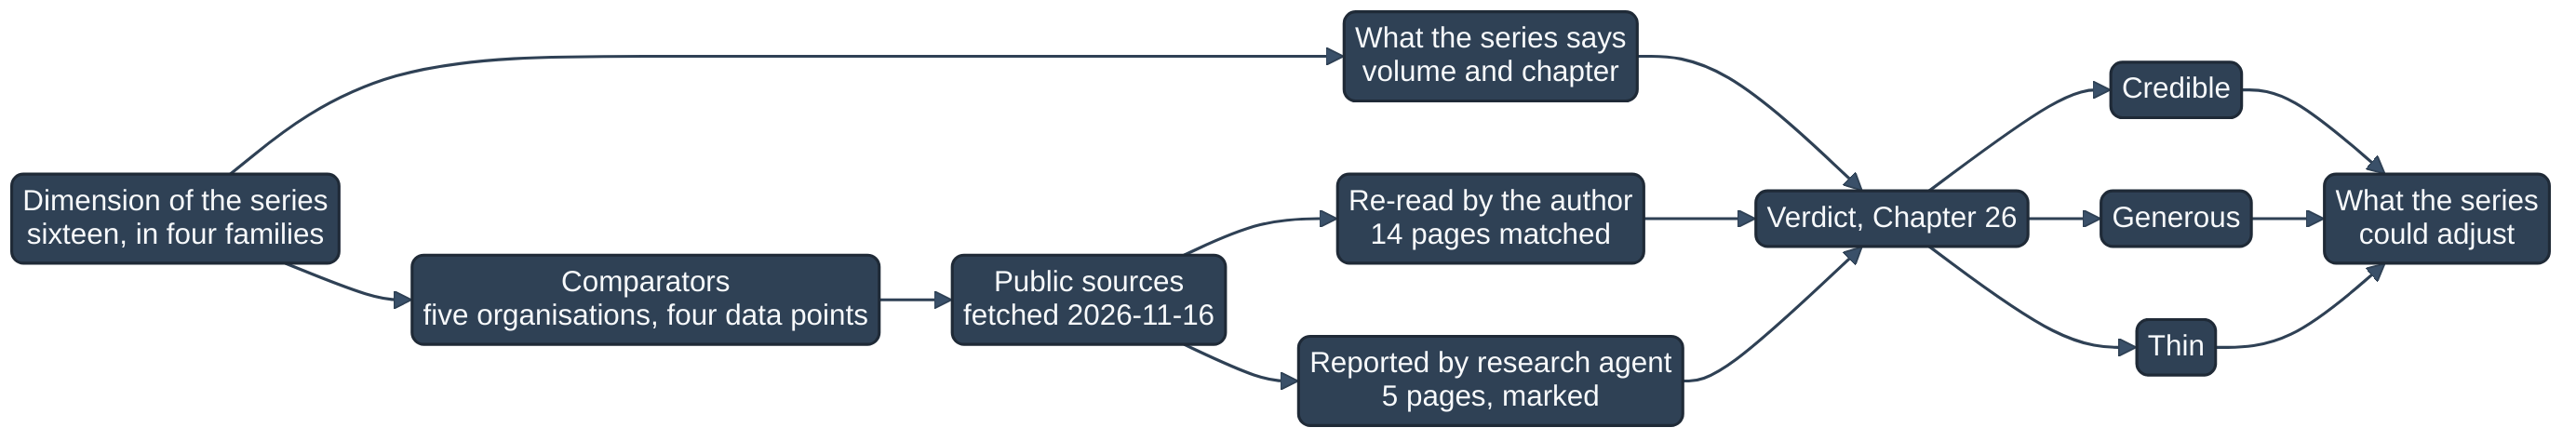
Figure 25.1: The method of the credibility check. Each dimension is taken from a volume, compared with public sources fetched on 2026-11-16, and ends in a verdict and a proposed adjustment.
Choosing the comparators
No real organisation matches Hansa Mutual on every dimension: a mutual group of this size that operates in seven countries, with a claims centre serving four of them and a group AI platform, has no direct counterpart among the organisations whose figures are public. Five were chosen to cover different parts of the profile, and four others serve as single data points.
| Organisation | Why comparable | Limitation |
|---|---|---|
| SIGNAL IDUNA (Dortmund and Hamburg) | German mutual group with roots in Hamburg; closest in size and form; publishes its use of generative AI | Business is described only for Germany; no claims centre in Poland found |
| BarmeniaGothaer (Cologne) | Describes itself as one of the largest German mutual associations; 7,500 employees, near Hansa's size | Germany only |
| Achmea (Zeist) | Large Dutch insurer; the cooperative claim could not be confirmed on the page read | Premium volume several times larger; headcount could not be verified |
| Helvetia Baloise (Basel) | A European insurance group with eight markets and FINMA supervision | Joint-stock company, not a mutual; merger completed in 2025 |
| Gjensidige (Oslo) | Nordic insurer in Norway, Denmark and Sweden, supervised in the EEA | Listed company |
| HUK-COBURG | Largest German motor insurer; a data point on motor scale and claims staffing | Motor focus; legal form and total staff not stated on the page read |
| Allianz, Zurich and AXA | Single data points on agent deployments and shared-service centres | Used only where named below |
Folksam and Länsförsäkringar, two Swedish mutuals, were considered because Hansa has a Swedish subsidiary and a mutual character. Their annual reports could not be read in the form retrieved, so they contribute nothing to the tables below.
What the comparators publish
Scale, form and markets
The figures below are those stated on the pages read. Where the page gives a different measure from the one Hansa uses, the difference is stated.
| Organisation | Premium or volume | Employees | Markets and form | Source |
|---|---|---|---|---|
| SIGNAL IDUNA | Contribution income EUR 7.2 billion (+3.1 per cent), 2025; total result EUR 537.5 million (previous year 553.7 million); investments about EUR 113.9 billion | "Over 11,000" including about 2,800 self-employed field partners and 372 trainees | Described in 2024 as a Gleichordnungskonzern; about 12 million insured persons and contracts | (17, Pfauntsch & W. K. / AUTOHAUS, 2026) (19, SIGNAL IDUNA, 2024) |
| BarmeniaGothaer | Premium income "rund 9,3 Milliarden Euro" (release boilerplate), 2025 | 7,500 | A Versicherungsverein auf Gegenseitigkeit; about 8 million customers | (20, BarmeniaGothaer AG, 2025) |
| Achmea | Premium volume EUR 27.5 billion (+11 per cent), 2025 | Not verified | Not read on the retrieved page | (21, Achmea, 2026) |
| Helvetia Baloise | Pro forma combined business volume CHF 19,838.9 million, 2025 | About 22,000 | Eight European markets; a joint-stock holding; reduction of about 2,000 to 2,600 FTE by 2028, with slightly more than 1,100 FTE reached by the end of the first quarter of 2026 | (22, Helvetia Baloise Holding AG, 2026) |
| Gjensidige | Not compared (different measure) | About 4,700 | Norway, Denmark and Sweden | (23, Gjensidige Forsikring ASA, 2026) |
| HUK-COBURG | Gross contributions about EUR 11.0 billion; motor EUR 6.3 billion | Not stated; about 200 new posts, mainly in claims and benefits, in the year | About 13.6 million customers; 14.5 million insured vehicles | (24, HUK-COBURG Versicherungsgruppe, 2026) |
Two readings are the author's own and are not source facts. SIGNAL IDUNA's "over 11,000" includes field partners and trainees; removing both gives about 7,800 employees, which is a lower bound because the source says "over". And the series gives no premium volume for Hansa Mutual. The peers with employee counts near Hansa's (BarmeniaGothaer at 7,500 and SIGNAL IDUNA at about 7,800) report premium or contribution income of EUR 7.2 to 9.3 billion, which suggests the range into which a Hansa premium figure would fall if the series ever stated one. That is an inference, not a measurement.
Supervisors and surveys
The supervisory evidence matters more than the company figures, because Hansa's governance claims are claims about what supervisors expect.
| Source | What it says | Retrieved |
|---|---|---|
| EIOPA, Opinion on AI governance and risk management, 6 August 2025 | Follows "a risk-based and proportionate approach"; addressed to national supervisors; states that "AI systems used for risk assessment and pricing in life and health insurance are deemed as high-risk under the AI Act"; high-risk and prohibited systems are outside the Opinion's scope (25, EIOPA, 2025) | 2026-11-16 |
| EIOPA Chair Petra Hielkema, speech, 15 April 2026 | "65% of insurance undertakings are already actively using GenAI systems"; "more than a third of firms are already developing customer-facing applications such as chatbots or voice assistants"; "Most use cases are still at the proof-of-concept stage"; agentic systems "are expected to grow significantly over the medium term" (26, Hielkema & P. / EIOPA, 2026) | 2026-11-16 |
| Bank of England and FCA, Artificial intelligence in UK financial services - 2024, 21 November 2024 | 118 responses; "The insurance sector reported the highest percentage of firms currently using AI at 95%"; "A third of all AI use cases are third-party implementations"; "Only 2% of use cases have fully autonomous decision-making" (27, Bank of England and Financial Conduct Authority, 2024) | 2026-11-16 |
| FINMA, Guidance 08/2024, 18 December 2024 | "most financial institutions are still in the early stages of development"; governance and risk management structures "are still being established"; institutions should identify, assess, manage and monitor AI risks (28, FINMA, 2024) | 2026-11-16 |
| Finansinspektionen, 6 December 2024 | 234 respondents; 84 per cent say employees use public generative AI tools; 22 per cent have AI systems in production or development; of those with AI in production, 41 per cent have a formally approved policy (29, Finansinspektionen, 2024) | 2026-11-16 |
| BaFin guidance on ICT risks in the use of AI, 18 December 2025, as reported | Non-binding; addressed to credit institutions and Solvency II insurers; DORA focus on ICT risk management and ICT third-party risk (32, IT Finanzmagazin, 2025) | 2026-11-16 |
| Finanstilsynet (Norway), survey of insurers' use of advanced technology | 31 insurers; eight report "omfattande bruk" (extensive use); expectation of sufficient human oversight; publication date not on the page, the address indicates 2024 (33, Finanstilsynet (Norway), 2024) | 2026-11-16 |
| ESAs, first report on DORA major ICT-related incidents, 3 June 2026 | 3,383 major incidents reported by financial entities in the EU, "0.18 per entity subject to DORA"; about a third with cross-border impact; "Only 10%" related to cybersecurity; "System failures and external events were the main drivers" (30, EBA & EIOPA and ESMA, 2026) | 2026-11-16 |
The Swedish figures cover the financial sector as a whole and not insurance alone. The ESAs' ratio is a count per entity for the reporting period of the first report. The page read does not state that period, so the ratio is not converted to a yearly rate here.
The legal frame the series gives Hansa can be read against these sources. AI Governance classes Hansa's underwriting-support model for life and health as high-risk under Annex III point 5(c) of the AI Act, which lists AI systems intended for risk assessment and pricing of natural persons in the case of life and health insurance; EIOPA's statement above says the same of the instrument. The series also places the register of information and exit strategies for third-party ICT services under Articles 28(3) and 28(8) of Regulation (EU) 2022/2554 (DORA), which require the register at entity, sub-consolidated and consolidated level and exit strategies for services supporting critical or important functions (AI Governance, Chapters 6 and 7) (2, Nordqvist, 2026). Both article references were read against the authentic text of the instruments for this chapter. They are architectural implications for the fiction, not legal advice.
Published AI deployments
| Organisation | What is published | Source |
|---|---|---|
| SIGNAL IDUNA | A generative knowledge assistant for private health insurance staff, built on Google Gemini and Vertex AI, with about 30 per cent less search time, about 80 to 85 per cent correct answers (medium-term target about 90 per cent), over 2,000 documents, and "smart agents" planned in other business areas (18, SIGNAL IDUNA, 2025) | 2025 |
| Allianz | Project Nemo, launched in Australia in July 2025: seven task-specific agents (planner, cyber, coverage, weather, fraud, payout, audit) for simple claims under AUD 500, live in under 100 days; "payout decisions are never automated"; Allianz reports an 80 per cent reduction in processing and settlement time (31, Allianz SE, 2025) | 2025 |
| Zurich | Agentic underwriting triage in five countries within 90 days, manual triage reduced from 75 to 15 minutes, extension to more than 20 markets planned; trade-press report of a vendor partnership, so vendor-sourced (35, FinTech Global, 2026) | 2026 |
| AXA | A shared-service centre in Warsaw and Kraków with about 2,200 staff since 2009, for finance, HR, IT and customer operations for European markets; the aggregator profile does not say it handles claims (34, Business of GCC, 2026) | 2026 |
The Allianz page says "launched in Australia in July 2025" and "in under 100 days"; the second phrase is about build time and the page does not state how long the system had been in operation.
What could not be found
The check found nothing for the following, and the verdicts in Chapter 26 treat each as thin or as "no reference found".
- A European insurer's claims agent or IT-operations agent with write access to production systems, published with its permissions, stop path and incident record. Allianz's agents are narrower than Hansa's triage agent and are about claims, not operations.
- A published cost per answer, a total cost for an assistant that drafts claims correspondence, or a daily cap on spend. Retail prices of office-suite assistants appeared only in search summaries and were not read.
- A comparable daily claims volume. HUK-COBURG publishes customers and vehicles; none of the pages gives claims per day.
- The size of a group AI platform team at an insurer.
- A claims-handling centre in Poland serving several markets. The AXA profile shows a shared-service centre of that general kind without claims handling.
- Evidence on employee representation at the comparators.
- Annual reports of Achmea (financial supplement), Folksam and Länsförsäkringar, whose PDFs could not be read.
- Several items surfaced only in search summaries and were not retrieved as pages: the UK Prudential Regulation Authority's January 2026 letter to insurers, the sample size of EIOPA's 2025 generative AI survey, and press reports of incidents at some insurers. None is used as evidence.
One public report concerns a claimed breach at a Hamburg insurer. It rested on an extortion group's assertion and the company had not confirmed it. The dossier does not use it, and no fact about any real incident enters the comparison.
How the sources were checked
A research agent fetched the pages and recorded what each said; the author of this chapter then re-fetched a sample and compared the wording. The re-check covered Allianz Nemo, the EIOPA speech and Opinion, the Bank of England and FCA survey, the ESAs' DORA report, the SIGNAL IDUNA result report and knowledge-assistant release and 2024 release, the BarmeniaGothaer release, the Finansinspektionen report, HUK-COBURG, Helvetia Baloise, Achmea (premium volume only) and FINMA, fourteen pages in all. Every figure in the tables above for those pages matched, with three corrections: the Achmea annual-results page does not mention cooperative identity, so the claim was dropped; the SIGNAL IDUNA 2024 release names the form "Gleichordnungskonzern" in its boilerplate without giving a more specific legal name; and Allianz's "under 100 days" refers to build time. Five pages were not re-read by the author and are marked here as reported by the research agent: Gjensidige, the BaFin guidance (through a trade-press summary), Finanstilsynet, the Business of GCC profile of AXA and the Zurich report.
| Source | Checked by the author | Note |
|---|---|---|
| 16 SIGNAL IDUNA result | Yes | Figures as quoted |
| 17 SIGNAL IDUNA knowledge assistant | Yes | Figures as quoted |
| 18 SIGNAL IDUNA 2024 | Yes | Form named only as Gleichordnungskonzern |
| 19 BarmeniaGothaer | Yes | Boilerplate says "rund 9,3 Milliarden Euro" |
| 20 Achmea | Yes, premium volume only | Cooperative identity not on this page |
| 21 Helvetia Baloise | Yes | Pro forma, unaudited |
| 22 Gjensidige | No | Reported by the research agent |
| 23 HUK-COBURG | Yes | Motor share of about 57 per cent is a division of the two published figures, not a stated figure |
| 24, 25 EIOPA | Yes | Quotations exact |
| 26 Bank of England and FCA | Yes | Quotations exact |
| 27 FINMA | Yes | Quotations exact |
| 28 Finansinspektionen | Yes | Whole financial sector, not insurance only |
| 29 ESAs | Yes | Reporting period not stated on the page |
| 30 Allianz | Yes | Build time, not operating time |
| 31 BaFin (trade press) | No | Secondary source for a supervisory text |
| 32 Finanstilsynet | No | Date inferred from the address |
| 33 AXA profile | No | Aggregator, not the company |
| 34 Zurich | No | Trade press on a vendor partnership |
The distinction between a primary and a secondary source matters for the verdicts. A verdict that rests only on a source marked "No" above is weaker, and Chapter 26 says so in its table.
Summary
This chapter fixed the terms of the credibility check. The check asks whether a fictional mutual insurance group with 9,500 employees in seven countries is plausible by public evidence, using five comparators (SIGNAL IDUNA, BarmeniaGothaer, Achmea, Helvetia Baloise, Gjensidige) and four data points (HUK-COBURG and, for AI deployments, Allianz, Zurich and AXA), plus the publications of EIOPA, the Bank of England and the FCA, FINMA, Finansinspektionen, Finanstilsynet, BaFin and the three European supervisory authorities. Sixteen dimensions are taken from the series, and each receives a verdict of credible, generous or thin in Chapter 26. The evidence supports scale, form and the supervisory frame well. It supports the agent deployments only in narrower forms than the series describes, and it provides no reference at all for costs, claims volumes, a group AI platform team size, a claims centre in Poland or an IT-operations agent with write access. These are conclusions of the dossier. Real organisations were used only as comparators, a fiction cannot be wrong about itself, and what the check measures is distance from the evidence.
Sources
- Nordqvist, G. AI Governance. (2, Nordqvist, 2026)
- Nordqvist, G. AI Boss. (7, Nordqvist, 2026)
- Nordqvist, G. AI Operations. (10, Nordqvist, 2026)
- Nordqvist, G. AI Developer. (12, Nordqvist, 2026)
- Pfauntsch, W. K. Bilanz 2025: SIGNAL IDUNA mit geschichtsträchtigem Ergebnis. (17, Pfauntsch & W. K. / AUTOHAUS, 2026)
- SIGNAL IDUNA. KI in den Kundenservice. (18, SIGNAL IDUNA, 2025)
- SIGNAL IDUNA. SIGNAL IDUNA wächst zum vierten Mal in Folge über Markt. (19, SIGNAL IDUNA, 2024)
- BarmeniaGothaer AG. First financial year. (20, BarmeniaGothaer AG, 2025)
- Achmea. Annual results 2025. (21, Achmea, 2026)
- Helvetia Baloise Holding AG. 2025 performance. (22, Helvetia Baloise Holding AG, 2026)
- Gjensidige Forsikring ASA. Delivered on all financial targets for 2025. (23, Gjensidige Forsikring ASA, 2026)
- HUK-COBURG. Marktführerschaft in Kfz weiter ausgebaut. (24, HUK-COBURG Versicherungsgruppe, 2026)
- EIOPA. Opinion on AI governance and risk management. (25, EIOPA, 2025)
- Hielkema, P. Supervising innovation in insurance. (26, Hielkema & P. / EIOPA, 2026)
- Bank of England and FCA. Artificial intelligence in UK financial services - 2024. (27, Bank of England and Financial Conduct Authority, 2024)
- FINMA. Guidance 08/2024. (28, FINMA, 2024)
- Finansinspektionen. AI increasingly common in the financial sector. (29, Finansinspektionen, 2024)
- EBA, EIOPA and ESMA. First report on DORA major ICT-related incidents. (30, EBA & EIOPA and ESMA, 2026)
- Allianz SE. How Agentic AI Is Transforming Insurance Claims Processing. (31, Allianz SE, 2025)
- IT Finanzmagazin. BaFin veröffentlicht Orientierungshilfe zu IKT-Risiken. (32, IT Finanzmagazin, 2025)
- Finanstilsynet. Kartlegging av forsikringsføretaka sin bruk av avansert teknologi. (33, Finanstilsynet (Norway), 2024)
- Business of GCC. AXA Group GCC in Warsaw. (34, Business of GCC, 2026)
- FinTech Global. Zurich expands agentic AI rollout with Cytora partnership. (35, FinTech Global, 2026)